Skip to content


Jewelry Financing Options: A 2026 Guide
Table of Contents
- Understanding Jewelry Financing Options
- Buy Now, Pay Later Plans for Jewelry
- Installment Payments and Monthly Payment Plans
- Jewelry Layaway Plans: How They Work
- Jewelry Financing With Bad Credit
- How Financing Affects Your Credit Score
- Choosing the Right Financing Plan for Your Luxury Purchase
- Frequently Asked Questions
Last Updated: October 10, 2026
Understanding Jewelry Financing Options
Luxury jewelry can be expensive upfront. Jewelry financing options let you spread payments over time, making premium pieces more accessible. These range from buy now, pay later services to traditional installment plans and layaway arrangements, each with different terms, credit requirements, and total costs.
Pro Tip
Start by calculating your total budget, including any interest or fees. This prevents overspending and helps you compare true costs across different financing options.
Buy Now, Pay Later Plans for Jewelry
Buy now, pay later (BNPL) services let you take home jewelry immediately and pay in smaller installments over 4 to 12 weeks. Most charge no interest if you pay on time, though late payments trigger fees or retroactive interest. You'll typically need to pass a soft credit check, which doesn't damage your credit score.
Many retailers partner with BNPL services like Affirm. These services make premium jewelry more affordable without the long-term commitment of traditional financing.
BNPL's main advantage is flexibility and immediate access. The downside: missing a payment becomes expensive quickly, and the short timeline means higher monthly amounts than longer installment plans.
Watch Out
BNPL services report payment history to credit bureaus. Missed payments can lower your credit score significantly, so only commit to a payment schedule you can reliably meet.
Installment Payments and Monthly Payment Plans
Traditional installment plans spread your purchase cost over months or years with a hard credit check and interest charges. You borrow the full purchase price and repay it in equal monthly chunks. The total you pay depends on the APR and repayment term, a lower APR and shorter term mean less total interest.
Understanding Total Borrowing Cost
When evaluating monthly payment plans, calculate the total repayment amount, not just the monthly payment. A plan with lower monthly payments might cost significantly more overall if the APR is higher or the term is longer.
For example, a 12-month term at 10% APR costs less total interest than a 24-month term at 15% APR, even though the monthly payment is higher. Comparing APR and term length together matters more than chasing the lowest monthly number.
Promotional Interest-Free Periods
Some lenders offer 0% APR for 6 to 18 months. If you pay off the balance before the promotional period ends, you owe no interest.
Fees and Hidden Costs
Beyond APR, watch for origination fees, late payment fees, and prepayment penalties. Always request a complete fee disclosure before signing.
Credit Check Impact
Installment loans require a hard credit inquiry, which temporarily lowers your credit score. However, making on-time payments rebuilds your score and demonstrates responsible credit use.
Most jewelry retailers offer installment options through third-party lenders. The key is comparing the APR, term length, and any fees before committing, and ensuring you can reliably meet every payment deadline.
Jewelry Layaway Plans: How They Work
Layaway is one of the oldest and simplest financing approaches. You select your jewelry, make a down payment, and the retailer holds it while you pay off the balance in installments. The main benefit is straightforward: no credit check, no interest charges, and no debt. The tradeoff is that you don't get your jewelry until you've paid in full.
Layaway terms vary by retailer. Always clarify the cancellation policy before committing to understand whether you can recover your payments or receive store credit if circumstances change.
Key Takeaway
Layaway is ideal if you want to avoid interest charges and debt, but only if you're confident you'll complete the payments. The lack of credit-building benefit means this option doesn't improve your credit score.
Jewelry Financing With Bad Credit
If your credit score is low or imperfect, you still have financing options for luxury jewelry. Some lenders specialize in financing for customers with bad credit, though they typically charge higher interest rates and may require a larger down payment.
Buy now, pay later services often use soft credit checks that don't impact your credit score. This makes BNPL a practical choice if you're concerned about your credit history. Layaway also requires no credit check at all, making it accessible regardless of your credit situation.
For traditional installment financing with bad credit, expect higher APRs and stricter terms. Some lenders require a co-signer or a larger down payment to offset the perceived risk. Shop around and compare offers from multiple lenders before accepting any terms.
The key is understanding that financing with imperfect credit doesn't have to mean predatory rates. Legitimate lenders offer reasonable terms even to customers with lower scores. The process just requires more diligence on your part to find the best deal.
How Financing Affects Your Credit Score
Taking on any form of credit affects your credit score, but the impact varies by financing type. Understanding these effects helps you make an informed decision about which option aligns with your financial goals.
Hard vs. Soft Credit Inquiries
Hard credit inquiries (used for installment loans and some BNPL services) can temporarily lower your score by a few points. Once you're approved, opening a new credit account also impacts your score initially, typically a 5-10 point dip.
Lab Diamond Basket 4 Prong Tennis Bracelet in 14K White Gold →
Soft credit checks (used by some BNPL providers) don't affect your score at all. Layaway and traditional lease-to-own arrangements typically don't involve credit checks, so they have no direct impact on your credit score.
Payment Reporting to Credit Bureaus
Not all financing arrangements are reported to credit bureaus. Here's what typically happens:
- Installment loans: On-time payments are reported and help build credit history. Missed payments are also reported and can lower your score by 100+ points.
- Buy now, pay later: Most BNPL services report payment history to credit bureaus, especially if you miss a payment. Some report on-time payments too, which can help your score.
- Layaway: Typically not reported to credit bureaus, so it has no credit-building benefit.
- Lease-to-own: Varies by lender. Some report to bureaus; others don't. Always confirm the lender's reporting practices before signing.
If building or rebuilding credit is a goal, ask the lender upfront whether they report positive payment history. This turns your jewelry purchase into a credit-building opportunity.
Returns, Exchanges, and Refunds During Active Financing
One often-overlooked interaction: what happens if you return or exchange your jewelry while you're still paying off the financing agreement? This varies significantly by retailer and lender.
- Refund timing: Most retailers process refunds within 5-10 business days, but your lender may not credit your account immediately. You could still owe payments during this gap.
- Early payoff: If you return an item and receive a refund, you can typically use that refund to pay off your financing agreement early, eliminating future interest. Confirm there's no prepayment penalty.
- Exchange: If you exchange for a different piece at a different price, clarify whether the financing agreement adjusts or whether you need to refinance.
- Deposit forfeiture: Some retailers apply restocking fees or deposit forfeitures to returns, which may not be refunded to your financing lender. Read the return policy carefully.
Always review both the retailer's return policy and the lender's terms together. A piece may be returnable, but your financing obligation may not automatically cancel.
What to Do If Payments Become Difficult
Life circumstances change. If you're struggling to make payments on jewelry financing, here are your options:
- Contact the lender immediately: Don't wait until you miss a payment. Many lenders offer hardship programs, payment deferrals, or restructured terms if you reach out proactively.
- Ask about forbearance or deferment: Some lenders allow you to pause or reduce payments temporarily without penalty, though interest may still accrue.
- Explore early payoff: If your financial situation improves, paying off the balance early eliminates future interest (assuming no prepayment penalty).
- Return the item: If the jewelry hasn't been altered or damaged, returning it may allow you to cancel the financing agreement and recover your down payment or payments made, depending on the retailer's policy.
- Refinance: If your credit score has improved, you may qualify for a lower-APR loan to pay off the original financing, reducing your total cost.
Missing payments on jewelry financing damages your credit score significantly and can stay on your report for seven years. This makes it harder to qualify for mortgages, auto loans, or other credit in the future.
Monitoring Your Credit Report
After you open a financing account, monitor your credit report for accuracy. You're entitled to one free credit report per year from each of the three major bureaus (Equifax, Experian, and TransUnion) at AnnualCreditReport.com.
Choosing the Right Financing Plan for Your Luxury Purchase
Selecting the right jewelry financing option depends on your credit situation, budget, timeline, and comfort with debt. Start by asking yourself three questions: How quickly do you need the jewelry? Can you afford the monthly payments?
If you need the jewelry immediately and have decent credit, a buy now, pay later plan or monthly installment option works well. BNPL is faster to approve and doesn't require a hard credit check.
If you prefer to avoid debt and interest charges entirely, layaway is your answer. You'll wait longer to receive your jewelry, but you'll owe nothing and build no debt. This approach also works if your credit score is low or nonexistent.
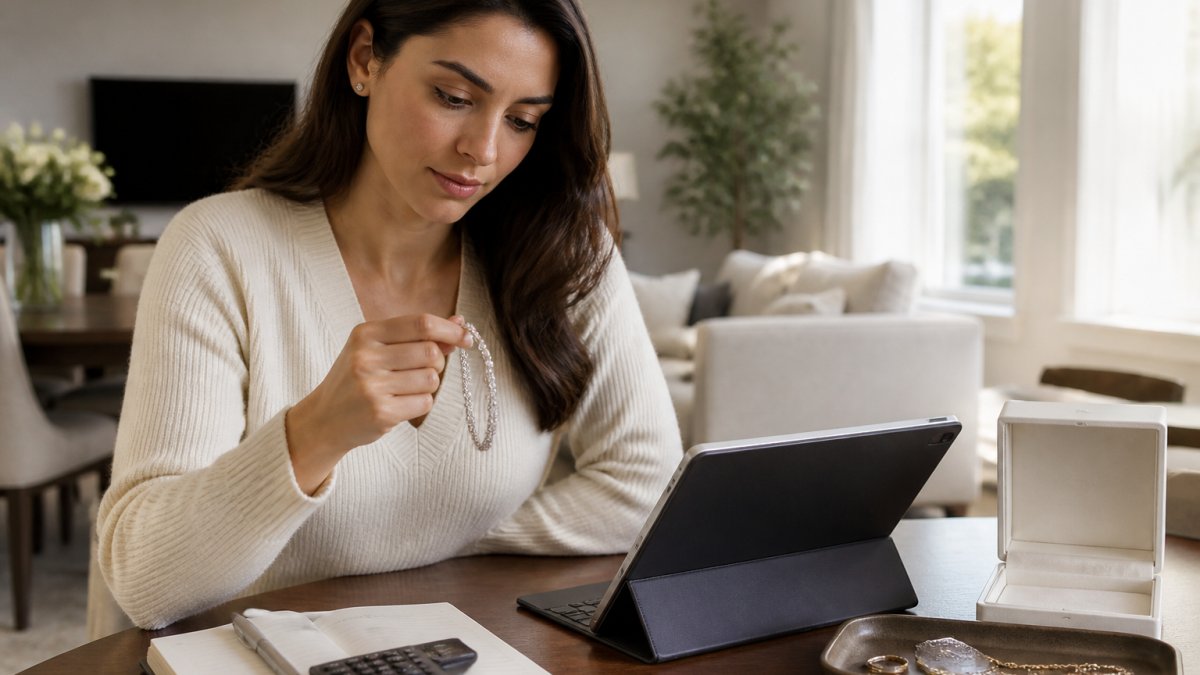
For high-value purchases like engagement rings or luxury bracelets, calculate the total cost of each financing option before deciding. A plan with a lower monthly payment might cost significantly more overall due to higher interest rates or longer terms.
Databazaar's flexible payment options with Affirm on orders over $50 give you the ability to choose terms that fit your situation. Whether you're purchasing the Lab Diamond Basket 4 Prong Tennis Bracelet in 14K White Gold or another premium piece, understanding your financing options ensures you make a choice you're comfortable with.

| Decision Factor | Best Option | Why |
|---|---|---|
| Need jewelry immediately | BNPL or installments | Fast approval and delivery |
| Want to avoid interest | Layaway | No interest charges |
| Bad credit | BNPL or layaway | Minimal or no credit checks |
| Long repayment period | Monthly installments | Spread payments over months |
| Want credit-building benefit | Monthly installments | On-time payments improve score |
The right financing plan aligns with both your immediate needs and your long-term financial health. Take time to compare options, read the terms carefully, and choose the approach that lets you enjoy your luxury jewelry without financial stress.
Finding the right way to finance luxury jewelry shouldn't be complicated. Whether you choose a buy now, pay later plan, monthly installments, layaway, or lease-to-own arrangement, the goal is the same: owning beautiful jewelry that fits your budget.
Frequently Asked Questions
What are the best ways to finance jewelry?
The best financing method depends on your credit score, purchase amount, and repayment timeline. Buy now, pay later plans work well for purchases over $50 with no interest if paid within the promotional period. Installment plans spread costs over 12-48 months with fixed monthly payments. Layaway requires no credit check but ties up your money until you pay in full. For those with imperfect credit, some retailers offer no-credit-check options or lease-to-own arrangements. Compare total repayment costs, approval requirements, and whether early payoff penalties apply.
Does jewelry financing affect your credit score?
Most jewelry financing does trigger a hard inquiry, which temporarily lowers your credit score by a few points. If you open a new credit account, it affects your credit mix and average account age. However, making on-time payments builds positive credit history and can improve your score over time. Layaway and no-credit-check options don't impact your credit at all. Buy now, pay later plans may or may not report to credit bureaus depending on the provider. Check with the lender before applying to understand the credit implications.
Can you finance jewelry with bad credit?
Yes, several options exist for those with bad credit or no credit history. No-credit-check financing plans don't require a credit inquiry but often charge higher interest rates or fees. Layaway plans require no credit approval and let you reserve items by making deposits. Some retailers offer lease-to-own arrangements where you can own jewelry after completing payments. Alternatively, adding a cosigner with good credit to a standard financing application can improve approval odds. Compare terms carefully, as bad-credit options typically cost more overall.
What should I compare before choosing a jewelry payment plan?
Evaluate total repayment cost (principal plus interest and fees), monthly payment amount, payment term length, annual percentage rate (APR), credit requirements, approval timeline, and early payoff penalties. Check whether the plan reports to credit bureaus and impacts your credit score. Confirm the retailer's return and cancellation policy if you change your mind. Verify whether insurance or protection plans are included or optional. Finally, ensure the monthly payment fits comfortably in your budget without overextending yourself financially.